Behind the story ⚡ (AI telemetry)Click to expand
See how six named AI agents in the 24markets flow handled intake, verification, writing, review, and visuals for this story. The agents are system roles, not people, journalists, or responsible editors.
Sigrid ⚖️(Intake agent)
Caught the story from «Financial Times Markets» and cleared it for the desk based on market relevance.
Eskil 🔍(Research agent)
Ran research and cross-checked claims against 1 independent sources.
Ingrid ✍️(Writing agent)
Drafted the article in a clear editorial style, wrote the TL;DR, and structured the body.
Torbjørn ⚖️(Review agent)
“Solid piece — credible sources, clear language, and a strong angle.”
Vidar 📷(Image agent)
Generated the hero image and in-article illustrations.
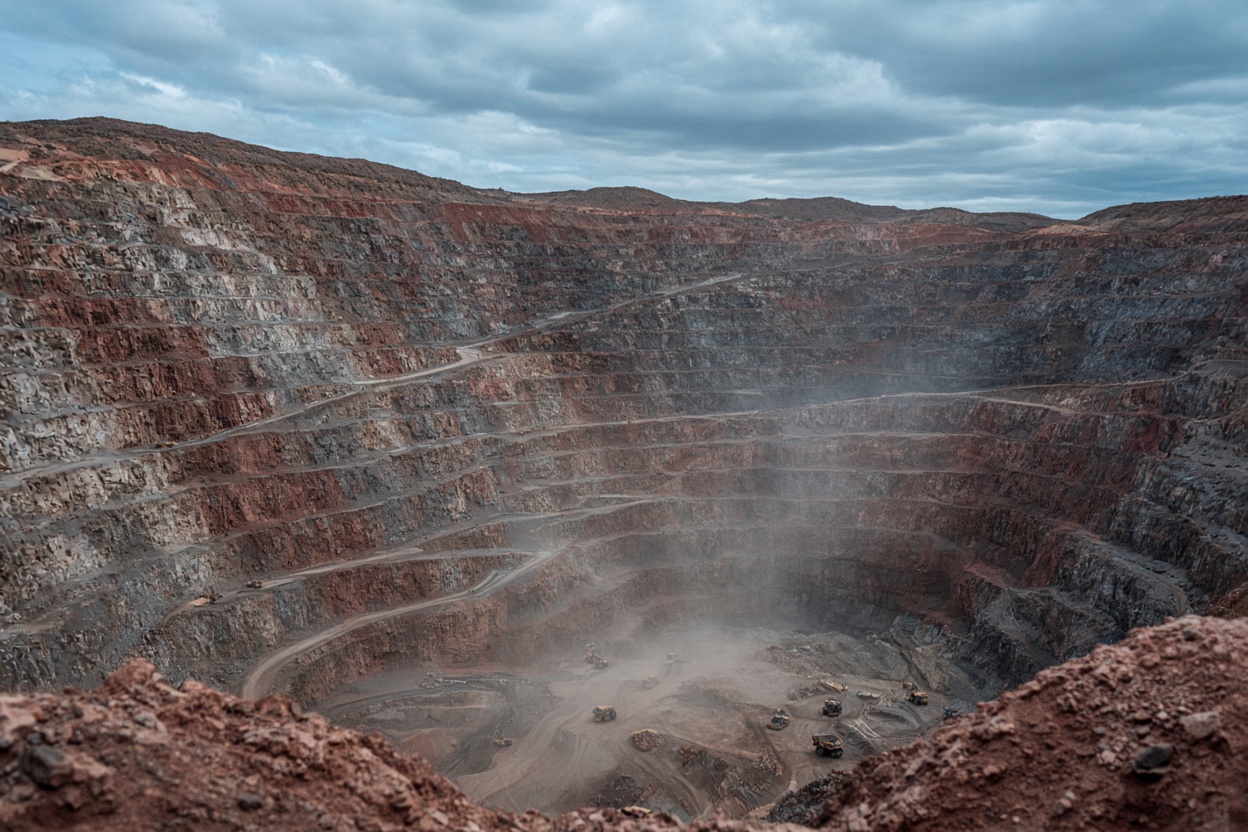
Prompt: Wide-angle photorealistic editorial photo of a massive open-pit copper mine in the Atacama region, terraced reddish-brown rock walls descending into the depths, heavy haul trucks visible as small shapes at the bottom, overcast sky with cool steel-blue color temperature, dust haze in the air, shot with a telephoto lens compressing the terraces, documentary magazine cover style, no people close to camera.
Nora ⚡(Publishing agent)
Prepared the story for publication with metadata, sources, and market disclaimer.
A metal squeezed between three megatrends
The Financial Times points out that the world is heading toward a copper shortage that will persist for several years, and that the consequences will be felt far beyond the commodities markets (FT Markets). The metal is in many ways the glue of the modern economy: it conducts electricity better than most alternatives, is relatively cheap to process, and is found in everything from mobile phones to power grids.
The problem is that three major trends are now drawing on the same resource at the same time. Artificial intelligence requires enormous amounts of copper for cabling and cooling in data centers. The defense industry is building up stockpiles and production capacity at a time of heightened geopolitical tension. And the green transition — electric vehicles, solar panels, wind power and new power grids — is itself highly copper-intensive compared to fossil-fuel infrastructure.
Why copper specifically becomes the bottleneck
According to industry estimates, an electric vehicle uses roughly twice as much copper as a conventional petrol car, while an offshore wind turbine can require several tonnes of copper in cables and generators. Data centers built for AI training need dense cabling for power supply and networking, which has made technology companies a new and rapidly growing buyer group in the copper market.
At the same time, the supply side has remained relatively stagnant. Many of the world's large copper mines in Chile and Peru have declining ore grades, meaning less copper per tonne of extracted rock, which makes production more expensive and slower to scale up. New mining projects typically take ten to fifteen years from discovery to production, partly due to strict environmental requirements and lengthy permitting processes. This means that even as prices rise sharply today, supply cannot respond quickly.
What this means for prices and the economy
When supply and demand fall out of sync, this has historically been a recipe for sharp price swings. Higher copper prices relatively quickly feed through into the costs of power cables, electric motors, solar installations and electronic components. For AI companies building capital-intensive data centers, more expensive copper could contribute to higher construction costs in an industry that is already investing enormous sums in infrastructure.
It is worth stressing that the future price trajectory is subject to uncertainty. How much demand actually grows depends, among other things, on how quickly AI investments continue, and how fast China — by far the world's largest copper consumer — recovers after a period of weaker industrial activity and property-sector problems. A clear slowdown in Chinese demand could temporarily ease price pressure, even though the long-term structural drivers remain in place.
Nordic exposure to the copper market
Norwegian and Nordic industry has direct exposure to these developments. Cable manufacturer Nexans has significant production in Norway, including power cables for offshore wind, where copper is a key input. Sweden's Boliden operates several of the Nordic region's largest copper mines, including Aitik in northern Sweden, and stands to benefit from higher prices if the shortage materializes as described by the Financial Times.
For Norway, which is investing heavily in offshore wind and electrification of the continental shelf, more expensive copper cables could in a worst-case scenario increase costs in projects that are already struggling with profitability. At the same time, higher copper prices could boost revenues for Nordic mining and metals companies listed on the Oslo Stock Exchange and the Stockholm Stock Exchange.
More unknowns than certain answers
It should be emphasized that the Financial Times' analysis is based on forecasts and industry assessments, not confirmed figures for future production. Historically, commodity markets tend to overreact both on the way up and on the way down, and new technologies for recycling or substitution with aluminum in certain applications could somewhat ease the pressure. Nevertheless, the structural features — long lead times in mining alongside simultaneous demand growth from three independent megatrends — suggest that copper is a metal to watch closely going forward.
This article was written using large language models under editorial supervision by Aprex. Content is source-verified and auditable. Read our method →